Goodbudget: Budget & Finance
Dayspring PartnersFinanceVerified
- 4.87K Reviews
- 3.3
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
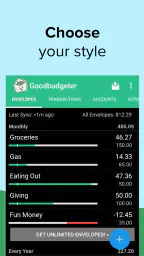
 Analysis by Appwesome
I like Goodbudget: Budget & Finance best when I treat it as a hands-on plan rather than a magic fix for money worries. Its envelope approach asks me to decide what my income needs to cover, then pay attention as I spend. That makes it a useful choice for people who want to be more deliberate with everyday purchases, though it does ask for regular input and a willingness to stick with the plan.
What the free starting point does—and what paid options mean
Goodbudget is a free finance app from Dayspring Partners, and its Everyone age rating makes it broadly accessible. In-app purchases are listed from $0.99 to $69.99 per item, so the app has optional paid items alongside its free access. I would begin by trying the free experience and deciding whether its budgeting style suits me before spending anything; the listed range alone does not tell me which purchase is worthwhile for a particular person.
The app has an average rating of 3.3 from around 19,000 ratings, with about 4,900 reviews, and more than a million installs. Those figures suggest that many people have tried it, but they are not a substitute for testing the workflow against my own needs. Its current version is 2.22.25023, and the minimum operating-system requirement is version 10.
Where the envelope method earns its keep
The central value here is the decision-making routine: assigning money to purposes before spending can make trade-offs visible. Instead of discovering at the end of the month that small purchases added up, I can check the relevant envelope first and decide whether the purchase fits. That is especially helpful when I am trying to balance flexible spending, such as dining out, against fixed commitments like rent.
This approach is different from a basic expense tracker, which often focuses on recording what has already happened. Goodbudget’s envelope structure encourages me to think ahead, then compare actual spending with that intention. A bank’s built-in tools may be more convenient for simply viewing transactions, while a spreadsheet can be more customizable; Goodbudget sits between those options, offering a defined budgeting method without requiring me to build the system from scratch.
Trade-offs to consider before committing
Envelope budgeting is only as useful as the information I enter and maintain. If I forget a purchase or leave an expense in the wrong category, the amount shown in that envelope becomes less dependable. That means the app works better as a routine than as a set-it-and-forget-it solution. I would also expect to spend some time choosing sensible categories and amounts at the beginning; an overly detailed setup can make the process feel like bookkeeping instead of help.
It may not be the right fit if I want a budget that runs almost entirely in the background or if my priority is a quick snapshot of account activity. Someone who prefers flexible, automatic categorization may find a bank tool or another tracker more comfortable. I would choose Goodbudget when the act of making spending decisions is the point, not when I merely want a record after the fact.
Other Stories to Read




Getting Started with Goodbudget
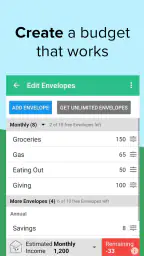
First things first, setting up Goodbudget is a breeze. After downloading it from the app store, you're greeted with a simple and clean interface. No clutter, just straight to the point. You start by creating your envelopes (more on those later) and entering your income. This is where the magic begins, my friends!
The app is based on the tried-and-true envelope budgeting system. If you're not familiar, it's a method where you allocate portions of your income to different categories (or envelopes) like groceries, rent, and entertainment. It's an old-school approach, but Goodbudget gives it a modern twist.
Features That Stand Out
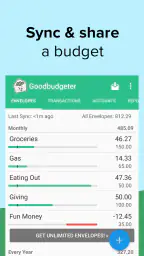
One of the standout features is the ability to sync your budget across multiple devices. This means you and your partner can track spending together and stay on the same page. No more awkward conversations about who's spending what!
That shared view is most useful when both people agree on what each envelope is for and update spending as it happens. I would keep the category names plain and specific enough to settle everyday questions: a grocery purchase belongs in groceries, while a shared dinner might need a household rule about whether it comes from dining out or entertainment. Agreeing on those small decisions early can prevent the budget from turning into a debate over labels.
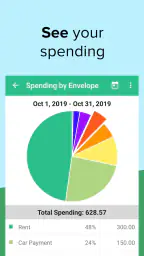
The reporting features are also quite nifty. With detailed reports, you can see where your money is going and make informed decisions about where to cut back. I found it eye-opening to see just how much I was spending on takeout every month. Yikes!
Reports become more useful when I treat them as a prompt for a concrete adjustment, rather than a verdict on past choices. If takeout is higher than I expected, I can decide whether to lower that envelope, plan meals differently, or leave the amount alone because convenience matters that month. Looking at a single category in context is more practical than trying to cut every flexible expense at once.
Another feature I love is the scheduled transactions. You can set up recurring expenses like rent or subscriptions, so they're automatically deducted from the relevant envelope. It's like having a financial autopilot.
For recurring costs, I would use scheduled transactions to protect the money for bills before deciding what is available for discretionary spending. It is still worth checking the envelope against real life: a subscription may change, a bill may be irregular, or a scheduled item may need correction. Treating the schedule as a planning aid, not a substitute for reviewing the budget, keeps the numbers useful.
Using the App Day-to-Day
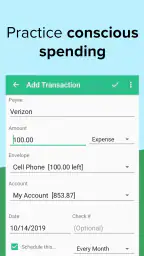
Day-to-day usage is smooth sailing. Entering transactions is quick and easy, and the app does a great job of reminding you if you forget. It's like having a responsible friend who nudges you to stay on track.
A realistic routine might be to check the grocery envelope before a weekly shop, record the purchase afterward, and then look at what remains before planning another run. If the balance is tight, I can adjust the next shop or consciously move money from a less important envelope. That small pause is where this method can change behavior; it turns a vague intention to “spend less” into a specific choice about which money is available.
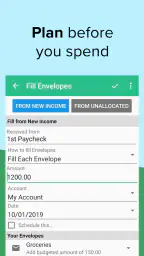
For irregular income, I would avoid filling envelopes based on an optimistic estimate. A safer routine is to budget against money that has actually arrived, then assign it according to priorities. This can feel slower than planning a whole month at once, but it reduces the risk of treating expected income as spendable cash. Anyone with uneven pay should test whether that deliberate, incremental process feels manageable before relying on it.
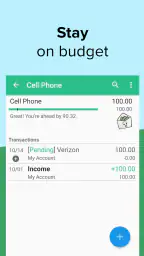
One thing I noticed is the sense of control it gives you. By visually seeing how much money you have left in each envelope, you're less likely to overspend. It's like the app is gently whispering, "Hey, maybe skip the second latte today."
That visibility also helps with competing goals. If I want to save for a trip while keeping room for ordinary treats, separate envelopes make the trade-off easier to see than one general balance. I can protect the savings contribution and still give myself a realistic amount for small pleasures. The useful lesson is not that every purchase is bad; it is that a purchase has to fit somewhere in a plan I have chosen.
Oh, and let's not forget about the community support. The Goodbudget community is active and helpful, making it easy to find tips and tricks to make the most out of the app.
Community advice can help me think through setup choices, but I would treat another person’s category system as inspiration rather than a template. Household income, bills, and priorities vary, so copying a detailed budget can create needless work. I would start with a small set of envelopes that answers my real spending questions, then add categories only when a recurring decision is hard to see in the existing setup.
Who is likely to get the most from it?
I would recommend this style to someone who wants a shared household plan, needs a visible limit for flexible categories, or is trying to build a habit of checking before spending. It can also suit a person who has tried tracking expenses but found that looking backward did not change what happened the next week. The envelope balance creates a direct link between the plan and the next decision.
It is less compelling for someone who dislikes manual attention, wants a highly customized spreadsheet, or needs budgeting to happen without regular check-ins. Couples should also be comfortable communicating about categories and transactions; syncing can make a plan visible across devices, but it cannot resolve different assumptions about what counts as an acceptable purchase. In that situation, agree on the budget together before relying on the shared view.
When choosing between Goodbudget and a bank’s built-in tracker, I would ask what problem I am trying to solve. A bank tool can be convenient for seeing account activity in one place, while Goodbudget is more purposeful about dividing money into planned uses. A spreadsheet may suit someone who wants total control over formulas and layout, but it takes more effort to create and maintain. Goodbudget’s appeal is the ready-made envelope framework; its cost is the attention that framework demands.
Wrapping It Up
In a world where our spending can easily spiral out of control, Goodbudget: Budget & Finance offers a breath of fresh air. It's simple, effective, and most importantly, it works. If you're looking to take charge of your finances without feeling overwhelmed, this app is a must-try.
My verdict is to try the free access if you are curious about envelope budgeting, then judge it by whether you actually keep the envelopes current and use them to make decisions. The listed in-app purchases mean paid options exist, but I would not assume they are necessary for every user or that a purchase will make the routine effortless. The value comes from a method you are willing to maintain, not from paying for the app alone.
Remember, budgeting doesn't have to be a chore. With Goodbudget, it's more like a game where you win by saving money and reducing stress. So, go ahead and give it a whirl. Your wallet will thank you!
Highlights
- User-friendly interface
- easy to navigate.
- Syncs across multiple devices seamlessly.
- Envelope system simplifies budgeting.
- Offers insightful spending reports.
- No ads in the premium version.
Limitations
- Limited features in the free version.
- No direct bank syncing available.
- Requires manual transaction entry.
- Some reports need premium access.
- May lack advanced financial tools.
Frequently Asked Questions
01What is Goodbudget and how does it work?
Goodbudget is a budgeting app that helps users manage their finances using the envelope method. It allows users to allocate funds into different virtual envelopes for various expenses, such as groceries or rent. This helps users track spending, save money, and avoid overspending by sticking to their budget allocations.
02Is Goodbudget available for both Android and iOS devices?
Yes, Goodbudget is available for both Android and iOS platforms. Users can download the app from the Google Play Store for Android devices and the Apple App Store for iOS devices. Additionally, Goodbudget offers a web version, allowing users to manage their budgets across multiple devices seamlessly.
03Does Goodbudget require an internet connection to function?
Goodbudget can function both online and offline. While an internet connection is needed to sync data across devices, users can still access their budget and log transactions offline. Once a connection is restored, the app will automatically sync the data to ensure all devices are up-to-date.
04Are there any costs associated with using Goodbudget?
Goodbudget offers a free version with essential features suitable for basic budgeting needs. For users seeking additional features, such as unlimited envelopes and accounts, a paid subscription is available. The subscription is billed monthly or annually, providing more flexibility and advanced tools for detailed budgeting.
05How secure is my financial information in Goodbudget?
Goodbudget prioritizes user privacy and security by using industry-standard encryption to protect financial data. The app does not link directly to bank accounts, which reduces the risk of unauthorized access. Users can rest assured that their information is securely stored and only accessible by authorized devices.


